Every Monday, we pull the five most-traded questions on Kalshi and Polymarket that actually settle inside the week, research them properly, and then make a prediction while including all our sources.
Each prediction gets a Geek Score from 0 to 100 depending on our level of certainty. Here’s the board for this week.
01. Will Iran and Oman announce a Hormuz management agreement by August 15?
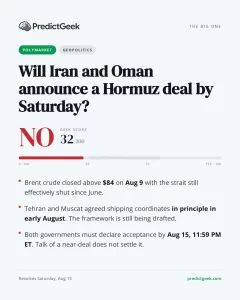
Polymarket · Resolves Saturday, August 15, 11:59 PM ET
Market price: 52¢ Yes
Our call: NO, Geek Score 32
The event page has taken more than $115,000 since it opened on August 4, about $85,000 of it on the August 15 leg. The August 31 leg trades at 75¢, so the crowd thinks the deal is coming and can’t agree on when.
The strait has been effectively shut since June, Brent closed above $84 on August 9, and the separate contract on traffic returning to normal by August 15 sits under 1¢. Tehran and Muscat reached agreement in principle on shipping coordinates in early August and are still drafting the interim framework.
Agreement in principle is not what’s being traded. The settlement bar is high: both governments have to make declarative statements accepting the same agreement, and statements referencing ongoing negotiations or a prospective deal explicitly do not count. Iran said on August 9 that a deal was close but not enough on its own to reopen the waterway, which is precisely the kind of statement the rules exclude.
Three things still have to land inside five days: inbound and outbound lane oversight, the fee structure, and sign-off from Iranian leadership. Tehran has also tied the file to Washington, wanting the naval blockade lifted first, and the contract on the US announcing an end to the blockade by the same date trades at 13¢. Frameworks in final drafting rarely get announced on a fixed five-day clock, and this one depends on something the market prices at 13%.
The risk: Oman is the region’s most effective back channel and has a record of producing announcements faster than anyone expected. If Muscat wants a signing moment it can manufacture one in 48 hours. We’re also fading a contract that moved sharply toward Yes in the last day, which usually means someone knows something. That’s why this sits at 32 and not lower.
02. Will July CPI come in at 3.3% year over year?
Polymarket · Resolves Wednesday, August 12, 8:30 AM ET
Market price: 40¢ Yes
Our call: NO, Geek Score 30
The BLS releases July CPI on Wednesday at 8:30 AM ET, the week’s biggest scheduled event for rates, equities and crypto. Polymarket’s annual inflation market has 3.3% at 40¢ and 3.4% at 37¢. Kalshi runs the same question through its CPI YoY series with deeper US liquidity, so check the ticker there first.
Economist consensus is 3.4%, slightly below June’s reading, with core seen at 2.5% against 2.6% previously. The crowd is pricing a softer print than the forecasters are. That’s the disagreement we’re taking.
The arithmetic is tight. June CPI fell 0.4% on the month and ran at 3.5% over the year, with gasoline doing most of the work on the downside. July 2025 printed +0.2% month over month, so for the annual rate to drop to 3.3% you need July 2026 to come in flat or negative. Polymarket’s own monthly contract puts 0.0% at 33¢ and -0.1% at just 5¢, which leaves roughly 60% of the distribution at +0.1% or higher. Those two markets are not telling the same story, and the monthly one is the more disciplined of the pair.
Energy argues the same way. June’s decline came from falling pump prices; July ran the other direction, with the Hormuz closure keeping WTI between $75 and $80 all month. A flat headline in that environment needs core services to do something it hasn’t done all year.
The risk: rounding. The gap between 3.3% and 3.4% can come down to a hundredth of a point in shelter, which has been decelerating steadily. If the monthly figure lands at +0.05% and rounds down, we lose on a coin flip no amount of research fixes.
03. Will Grok 4.6 be publicly available by August 14?
Polymarket · Resolves Friday, August 14, 11:59 PM ET
Market price: 84¢ Yes
Our call: YES, Geek Score 72
This is the thinnest call on the board. We agree with the direction the market is taking, not with how confident it is.
The contract settles Yes only if the model is genuinely available to the general public, verified against xAI’s release notes and product pages. Placeholder labels and closed betas don’t count. As of Monday morning, those notes still list Grok 4.5 as the latest flagship, and 4.5 shipped on July 16.
The bull case is the calendar. Musk said 4.6 would arrive around August 7. That date passed. On the August 4 SpaceX earnings call he said it was coming “probably next week,” which is this week, and that Grok 4.7 would follow three to four weeks later. A larger 4.7 queued behind it pressures 4.6 to ship now. The cadence fits: point releases every four to six weeks, and 4.6 is a post-training upgrade on the same 1.5-trillion-parameter foundation rather than a new base model.
The bear case is that Musk already missed his own first date here, and the companion contract for an August 7 release traded at 12¢ and settled No. Grok 5 is the longer-running version of the same pattern, slipping from Q1 and then Q2 2026 targets and still unshipped. When Musk gives a week, the hit rate looks closer to two thirds than five sixths. Two thirds is where we land, and 72 is an honest 70 rounded up.
The risk: if xAI slips to Monday the 17th, an entirely normal thing for a shipping org to do, this settles No by three days. At 84¢ the market pays almost nothing for carrying that risk, which is why our score sits well below the price even though our call matches it.
04. Will Scottie Scheffler win the FedEx St. Jude Championship?
Kalshi · Resolves Sunday, August 16
Market price: roughly 17% implied (Scheffler opened at +445 across sportsbooks Monday morning)
Our call: NO, Geek Score 19
The FedEx Cup playoffs open at TPC Southwind in Memphis from August 13 to 16, top 70 in the standings, no cut. Kalshi lists outrights on the event, so confirm the ticker before trading, since the naming changes between playoff stops.
Scheffler is world number one, FedEx Cup standings leader and the favourite at +445, ahead of Rory McIlroy at +970 and Xander Schauffele and Tommy Fleetwood at +1950. He also hasn’t won since the American Express in January, with five runner-up finishes among 11 top-fives this season. That’s why he’s trending, and why the “he’s due” case is everywhere this week.
Due isn’t a number. A 17% implied probability in a 69-player elite field is already a huge premium over the 1.4% a random entrant gets, and near the ceiling any golfer sustains over a season. Scheffler’s best result here in seven visits is solo fourth. The venue also finishes messily: four of the last five editions went to a playoff, and Justin Rose won last year’s at 16 under after beating J.J. Spaun in one. A playoff is exactly the mechanism that turns a favourite’s strong week into someone else’s trophy.
The risk: this is the least interesting kind of No. We’re not arguing Scheffler plays badly, only that somebody else wins roughly 83% of the time, which is what the price already says. If he has genuinely fixed the putter, fair value is closer to 22% and our edge shrinks toward nothing.
05. Will Trump’s approval rating be higher on August 14 than on August 7?
Polymarket · Resolves Friday, August 14, noon ET
Market price: 53¢ Up
Our call: NO, Geek Score 31
The market settles off the Silver Bulletin polling average, comparing the August 14 reading to August 7, with the confirming data point published the following day. The crowd has nudged a coin flip marginally toward Up.
The week’s inputs point the other way. The August 7 baseline was set on the morning the July employment report landed, and it was a large miss. Polling averages absorb events with a lag, because surveys fielded after the news still have to be published and weighted in. The polls that move this number by Friday are the ones going into the field right now, carrying that miss.
Scheduled news doesn’t help. CPI on Wednesday is expected to keep the annual rate above 3%, PPI lands Thursday, and Friday’s retail sales are forecast at just +0.2%. Pump prices stay elevated while Hormuz is shut, and gas has been the most consistent drag on these numbers all year, pushing net approval to around -18 earlier in the summer. With the midterms under 100 days out, nothing positive is scheduled between Monday and Friday.
The counterweight is real: the S&P 500 closed at a record on Friday and Iran de-escalation headlines have been broadly favourable. That’s what a 53¢ Up price is leaning on.
The risk: polling averages are sticky, and a one-week move is often smaller than the noise. If the average drops a stale low-approval poll out of its window, the number ticks up for mechanical reasons unrelated to the news. That alone probably accounts for a third of the outcomes here, which caps how confident anyone should be. This is the second thinnest call on the board.
The weekly scorecard
| # | Market | Platform | Resolves | Our call | Score |
|---|---|---|---|---|---|
| 01 | Iran-Oman Hormuz management agreement announced | Polymarket | Sat, Aug 15 | NO | 32 |
| 02 | July CPI prints 3.3% year over year | Polymarket / Kalshi | Wed, Aug 12 | NO | 30 |
| 03 | Grok 4.6 publicly available | Polymarket | Fri, Aug 14 | YES | 72 |
| 04 | Scheffler wins the FedEx St. Jude Championship | Kalshi | Sun, Aug 16 | NO | 19 |
| 05 | Trump approval higher on Aug 14 than Aug 7 | Polymarket | Fri, Aug 14 | NO | 31 |
We’re furthest from the crowd on the Hormuz deal, where the market pays 52¢ for a Yes that has to clear a settlement bar most of this week’s diplomacy has not come close to touching.
Disclaimer: Prediction markets carry real risk of loss. Nothing here is financial advice — it’s just our read on the publicly available information. Trade responsibly, and if it stops being fun, the National Council on Problem Gambling is at 1-800-GAMBLER.
